


Introducing the Signal in the Noise series. These pieces are data-driven analyses that cut through the chaos. We ask the right questions, run the numbers and tell you what it actually means.
The Underline:
In Short: GenAI booms, market shocks to retail and gamification mechanics - the state of mobile today is all about the economics of attention.
So What: The widest distribution channel is at our fingertips, but marketers, strategists and analysts need to know how to separate signal from noise to unlock its value.
The attention economy underpins our digital-first lives. It’s the premise that our attention is finite and scarce, and therefore our most valuable asset. It’s the operating system of modern life worth over $15 trillion in market value.
While this includes television, sports, events, computers, news and advertising across all form factors, it’s the mobile phone that led to an explosion of growth. A device that allows us to access any information at any time, and it’s in the palms of 70% of the world’s population.
To understand where mobile - and therefore our consumer behavior and attention at large - is going, we need to understand the patterns and market dynamics.
The State of Mobile 2026 Report by Sensor Tower is a great place to start.
We broke down three major takeaways for navigating the question plaguing marketers, advertisers and strategists: How do I win attention in 2026?
1. GenAI was the breakout star of the year, but not for everyone.
It’s no surprise that 2025 was the year of AI.
Demand surged in all facets:
App downloads: a measure of initial demand
Then usage: total sessions - how frequently you use the app, and time spent - a combination of frequency and depth of usage
And ultimately revenue: people are spending billions of dollars directly on GenAI services - in the US this is $20 / month or $200 per year. GenAI companies made $5 billion from app revenue, up a remarkable 229% YoY from $1.5 billion in 2024. Beyond direct consumer spend, ChatGPT will soon be making additional revenue from ads seen in their free tier or ChatGPT Go subscription.


However, we must also look at the nuance:
How do we access GenAI tools? In the US, over 213 million users accessed Generative AI tools - on web, app or a combination of both, but app is the medium of choice with 55% of Americans only using the app to access top AI assistants like ChatGPT, Google Gemini and Character AI, among others.
Who is really using GenAI apps? With stats like the above, it’s easy to fall into “everyone is using it” but that’s fundamentally not true. In fact there is a large gender and age differential in usage.
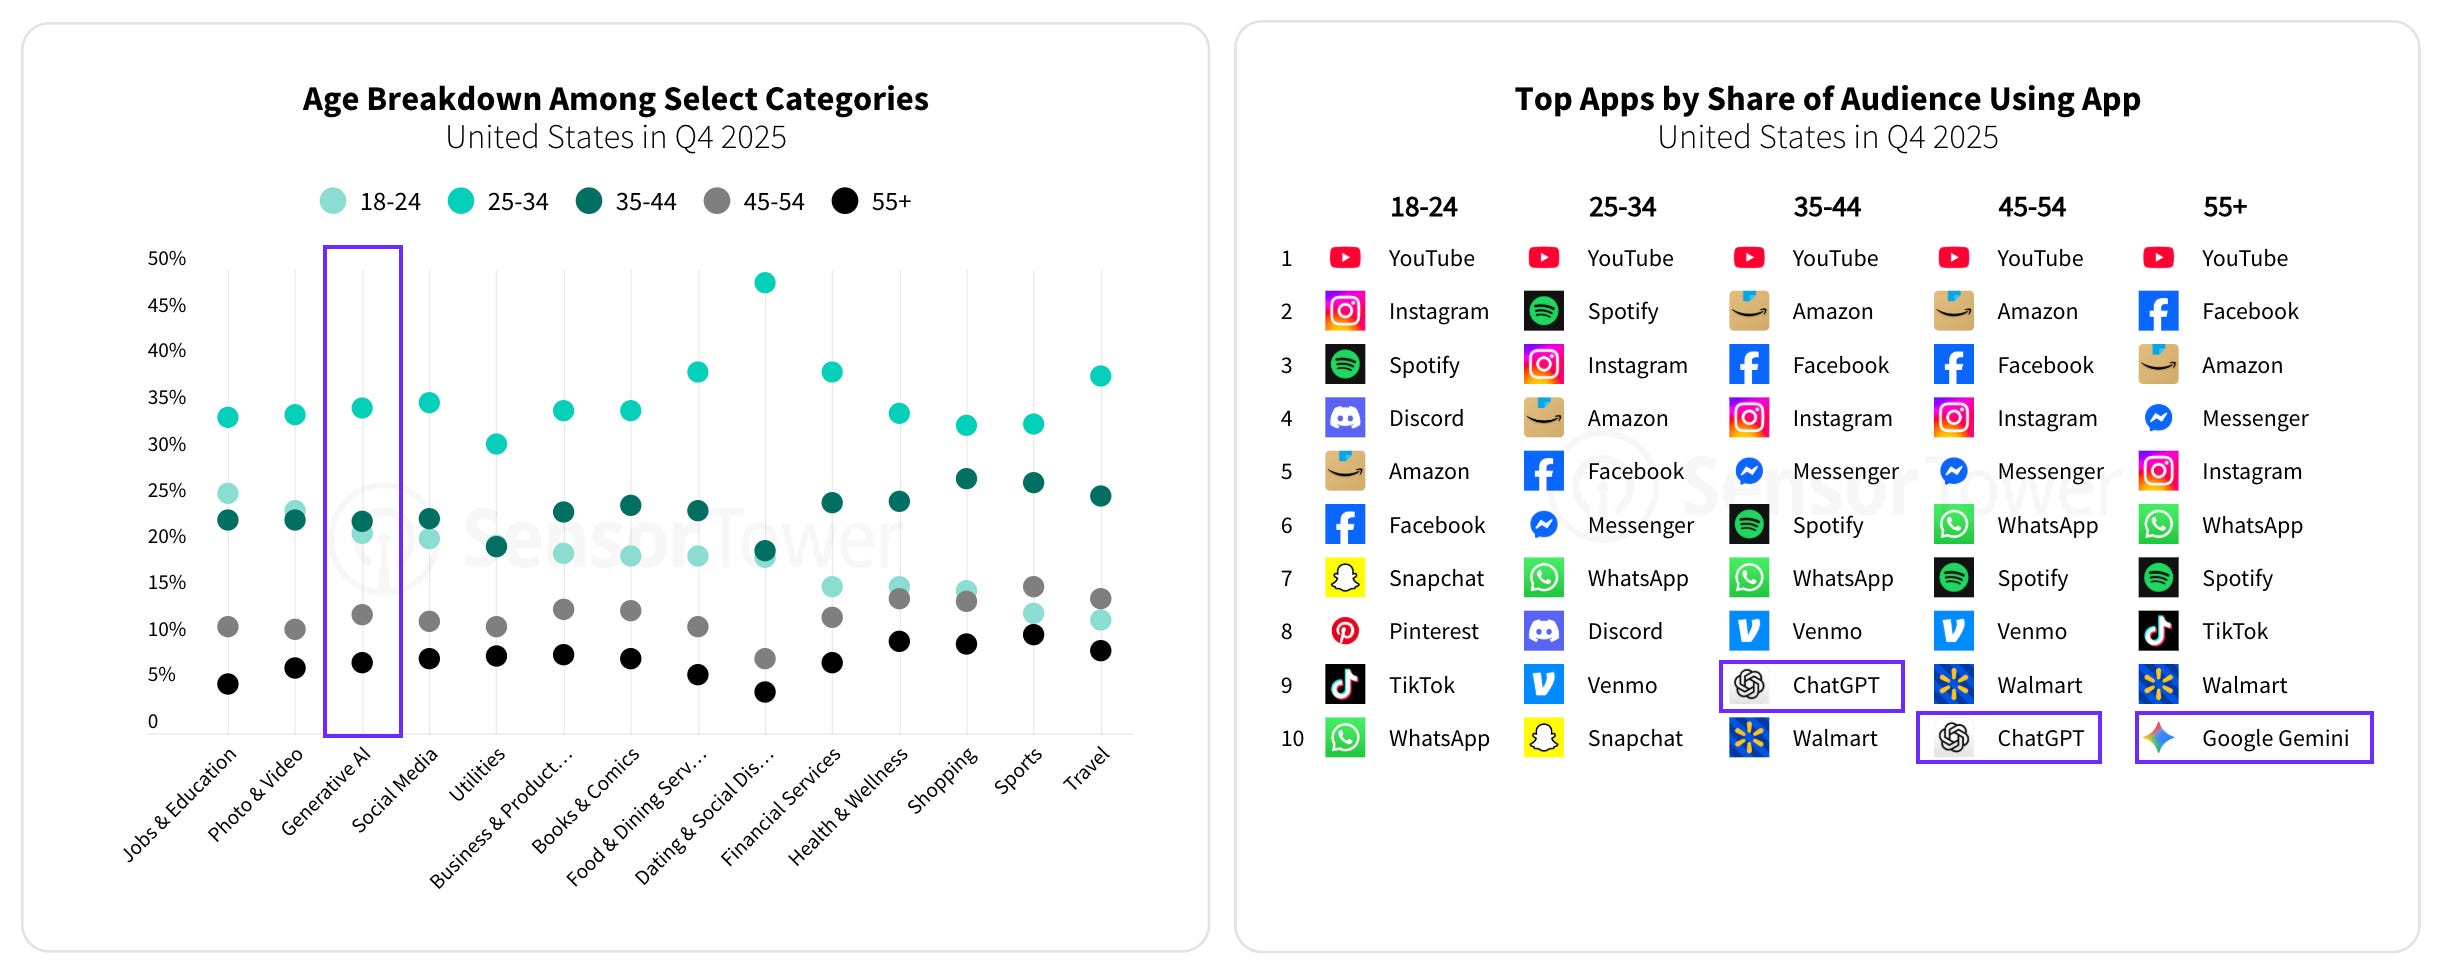
In the US, 25-34 year olds and 35-44 year olds represent the largest cohort of Gen AI users in Q4 2025, at approximately 35% and 22% of the audience respectively. GenAI only breaks into the top 10 most used apps for those aged 35+, not for younger users. Despite 25-34 year olds representing a large share of GenAI’s user base, they are heavy mobile users in general. Meaning, ChatGPT and Google Gemini don’t break into their top 10 because other apps have larger total users from this age group. Over half of Gen Z adults report AI makes them feel anxious, and over half of Gen Z (aged 13 - 28) are concerned AI will harm their critical thinking skills.
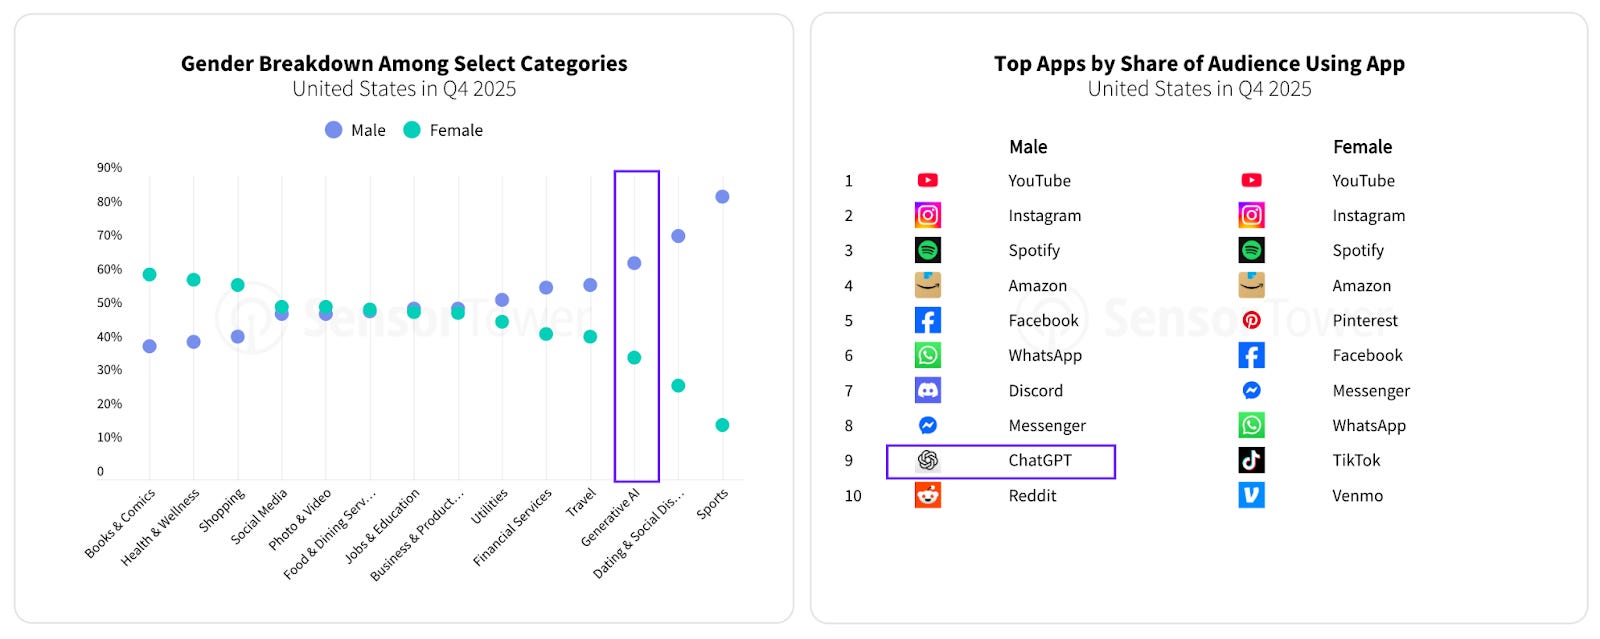
64% of GenAI users are male - with ChatGPT breaking into the most used apps by men at #9 (please note, gender is only represented by male and female and not representative of all gender identities).
A study by University of Oxford confirms these findings highlighting the gender gap emerging: women use GenAI substantially less often based on perceived risks to society and moral concerns including mental health, privacy, climate impact and the labor market.
Is there a favorite tool? Image and video generation become table stakes for any GenAI, but ChatGPT takes the lead by a factor of 3x for global cumulative app downloads (next in line is Google Gemini).
What’s next?
Google Gemini is being incorporated into the overall operating system of Android phones vs only within a standalone app - as is the case on iOS. We expect to see a greater push for AI to underpin offerings within big tech’s existing platforms, likely in a seamless way that overlays on existing views.
Wearables - glasses and earware (headphones) are the next battlegrounds for AI according to EMARKETER’s Jacob Bourne — bringing a slew of ethical and legal questions about “always on” AI.
What does this mean for larger consumer behavior?
Without regulation the AI gender gap could widen - threatening skills in the workplace and moral concerns for society at large.
Search looks a lot different, driven by AI overviews and summarized posts.
AI is unavoidable. With AI underpinning the tech that powers our most used services - email, search and socials - consumers need to be more vigilant not only in filtering out what is real vs AI, but pay careful attention to how they use technology, what content they produce that may be fueling AI, what is a verifiable source and what bias or lean AI, and its algorithms, could have. The US sale of TikTok is a recent example of the attention economy in action for downstream effects of algorithm control.
What does this mean for companies?
Advertisers/Marketers: Zero-click search is upon us. LLM referrals change the organic (and soon to be paid) discovery game, including Google’s AI overview. Answers are immediate and summarized and clicks don’t necessarily happen to read more on a website. Brands need to have a unique point of view and expertise to fuel traffic when the summary isn’t enough. The Anti-AI counterswing is also upon us - showing a boomerang back to raw, live and unfiltered experiences, think lo-fi creator content, in real life activations and anything that signals “a human is behind this”. AI is reshaping discovery but it’s not the whole picture. Understand where your specific audience spends attention and don’t put all your eggs in one AI basket. We wrote about the data-driven shift in consumer behavior here with how this will show up in 2026.
Product development: We are reshaping native behavior of search and discovery. Consumers are looking for a “concierge” or “assistant” experience, but not all consumers. Moral and ethical concerns govern usage, as well as bias in algorithms. The loudest voices in the room may have vested interests, larger podiums or access to tools to make a narrative travel, but it’s important not to neglect a large audience of folks who are finding and engaging with digital services outside of AI. Build flexibility into product design, test AI features against non-AI pathways and don’t mistake early adopter enthusiasm necessarily as mainstream readiness.
Corporate Strategy and Development: After a few years of hype, the AI race may meet a market correction. Strategies should be in place to mitigate market risks that are surfacing after the boom, whether this be market bubble concerns, chip shortages, infrastructure buckling (power and electricity grids), resource exhaustion (water inputs) - real estate for data centers, and public sentiment.
AI has undoubtedly boomed - changing the face of mobile, and the internet at large, forever. However, we should ensure we are still factoring in data-based consumer behavior, sentiment and market signals to ensure we are harnessing it in the right way, while minimizing our exposure to risks.
2. Tariffs and GenAI sent shockwaves through retail in 2025, but what rings true as we enter 2026? Price is still king.
Tariffs expose weaknesses in dominant m-commerce players
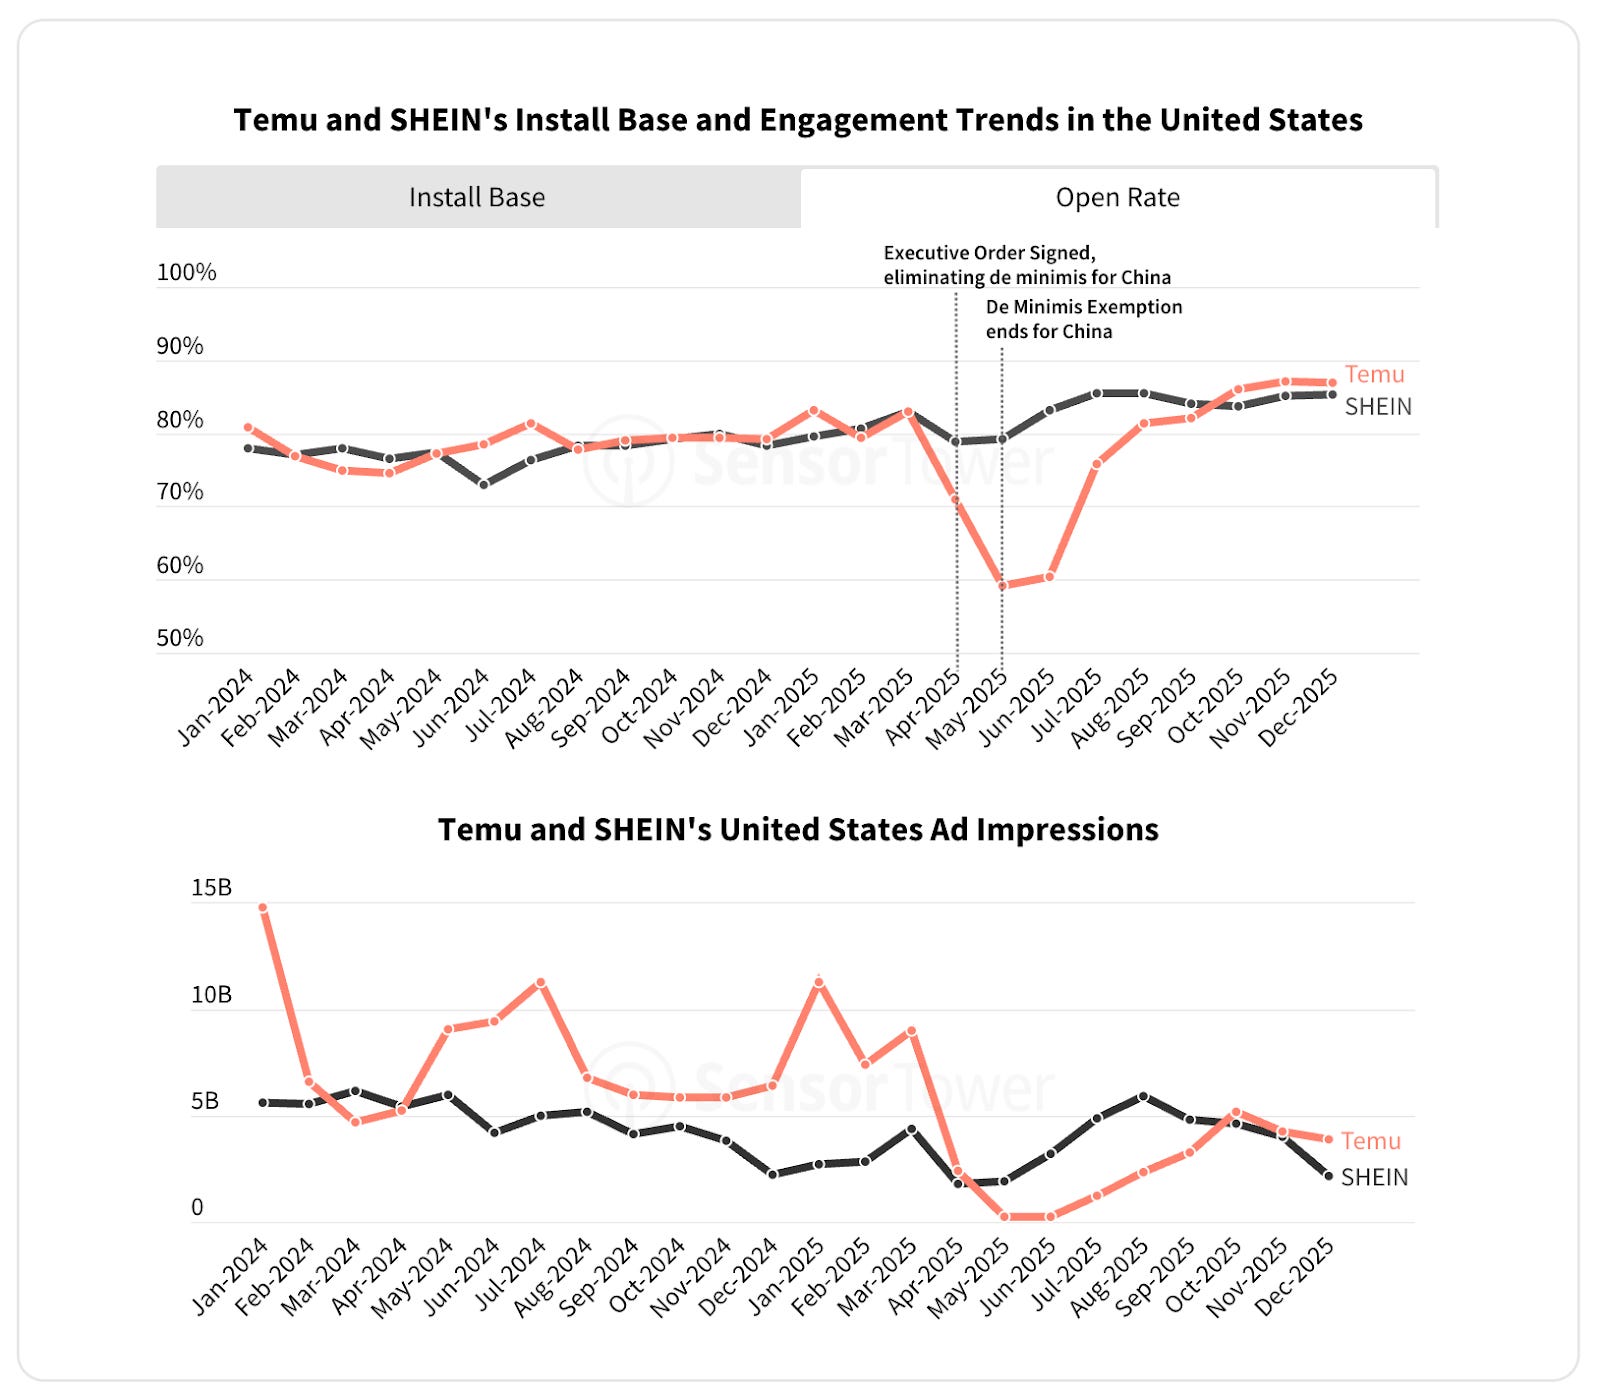
In a cost of living crisis, price is the winner. Temu and SHEIN remained the top two Shopping apps in the US by downloads, despite getting hit with the end of the De Minimis loophole - where goods under $800 could be imported in the US without duties. Additional tariff threats on China by Trump exaggerated the hit to the ecommerce giants. After both brands pulled back on ad spend in the US, SHEIN weathered the storm better - showing the resilience of building a loyal and engaged audience through its ‘social media-like’ features - a hallmark feature of the app. Price point is a critical input for shopping apps, especially as deal hunting has become sport, however, it’s not everything. A strong community, personalized experiences and loyalty rewards will help retain customers.
Retail: a marriage of offline and online engagement
Omnichannel is the name of the game, but the app is becoming the linchpin to success. 56% of all holiday shopping revenue (Nov - Dec 2025) happened on mobile, equal to $145 billion USD. With more AI users choosing apps over web, and growth of AI traffic referrals to retailers, we can expect mobile to continue to take over share of wallet.
GenAI website traffic referrals soar, but it’s still early days
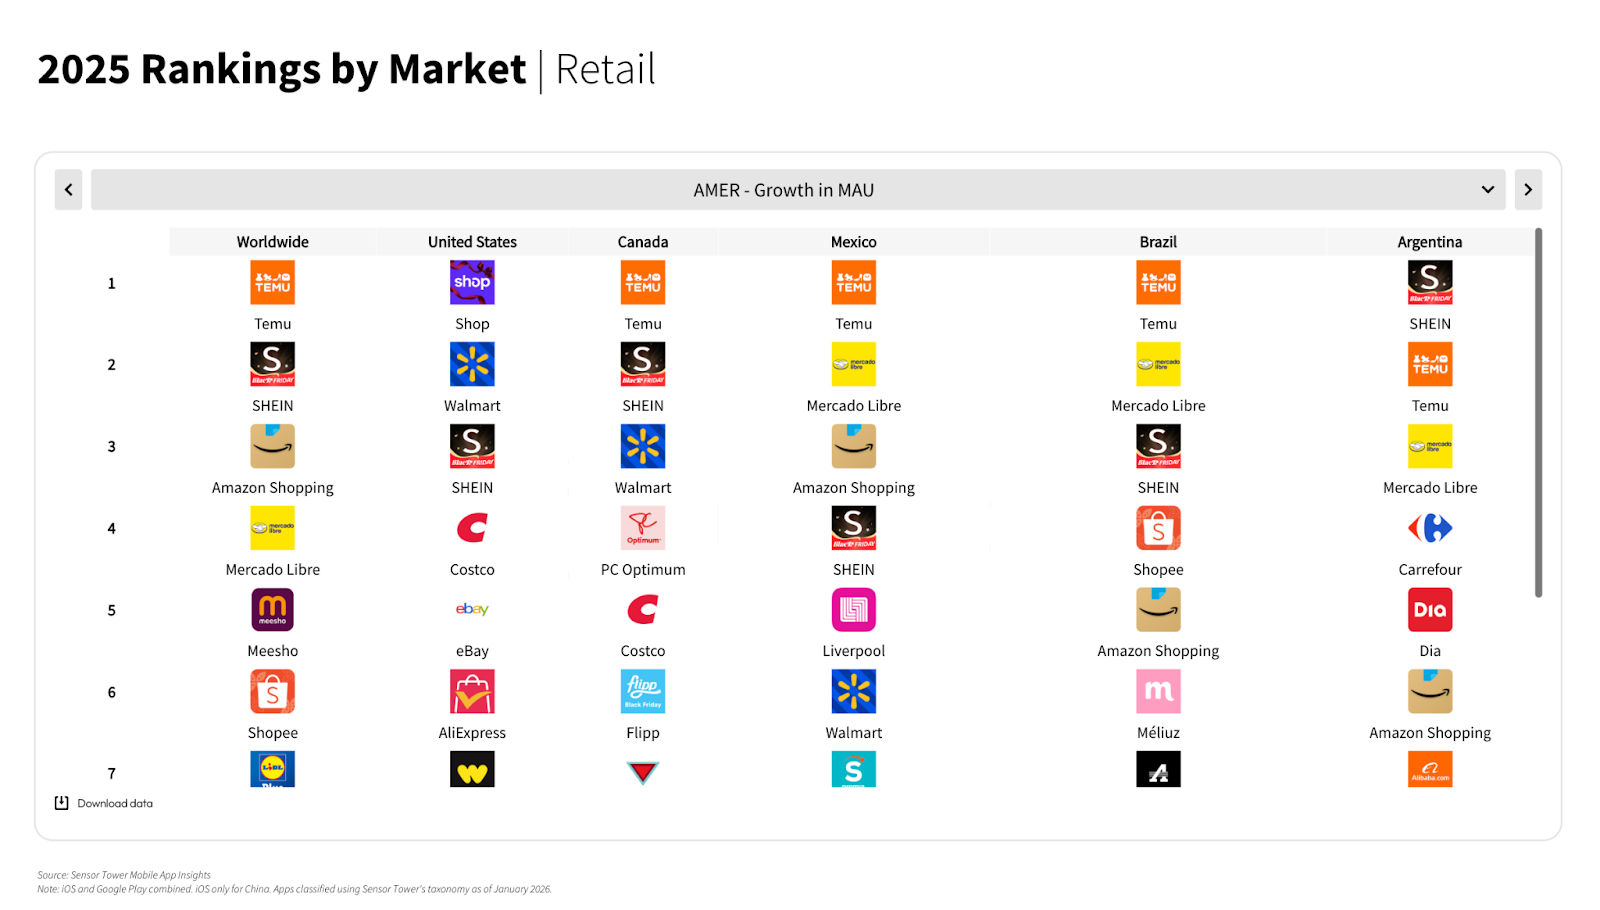
GenAI has referred 41 million visits to major e-commerce sites in the US in December 2025, up 7x within a year. However, this represents <1% of total retail traffic. Promising potential, but not the driving force of discovery, yet.
Trading in attention: Retail Media Networks
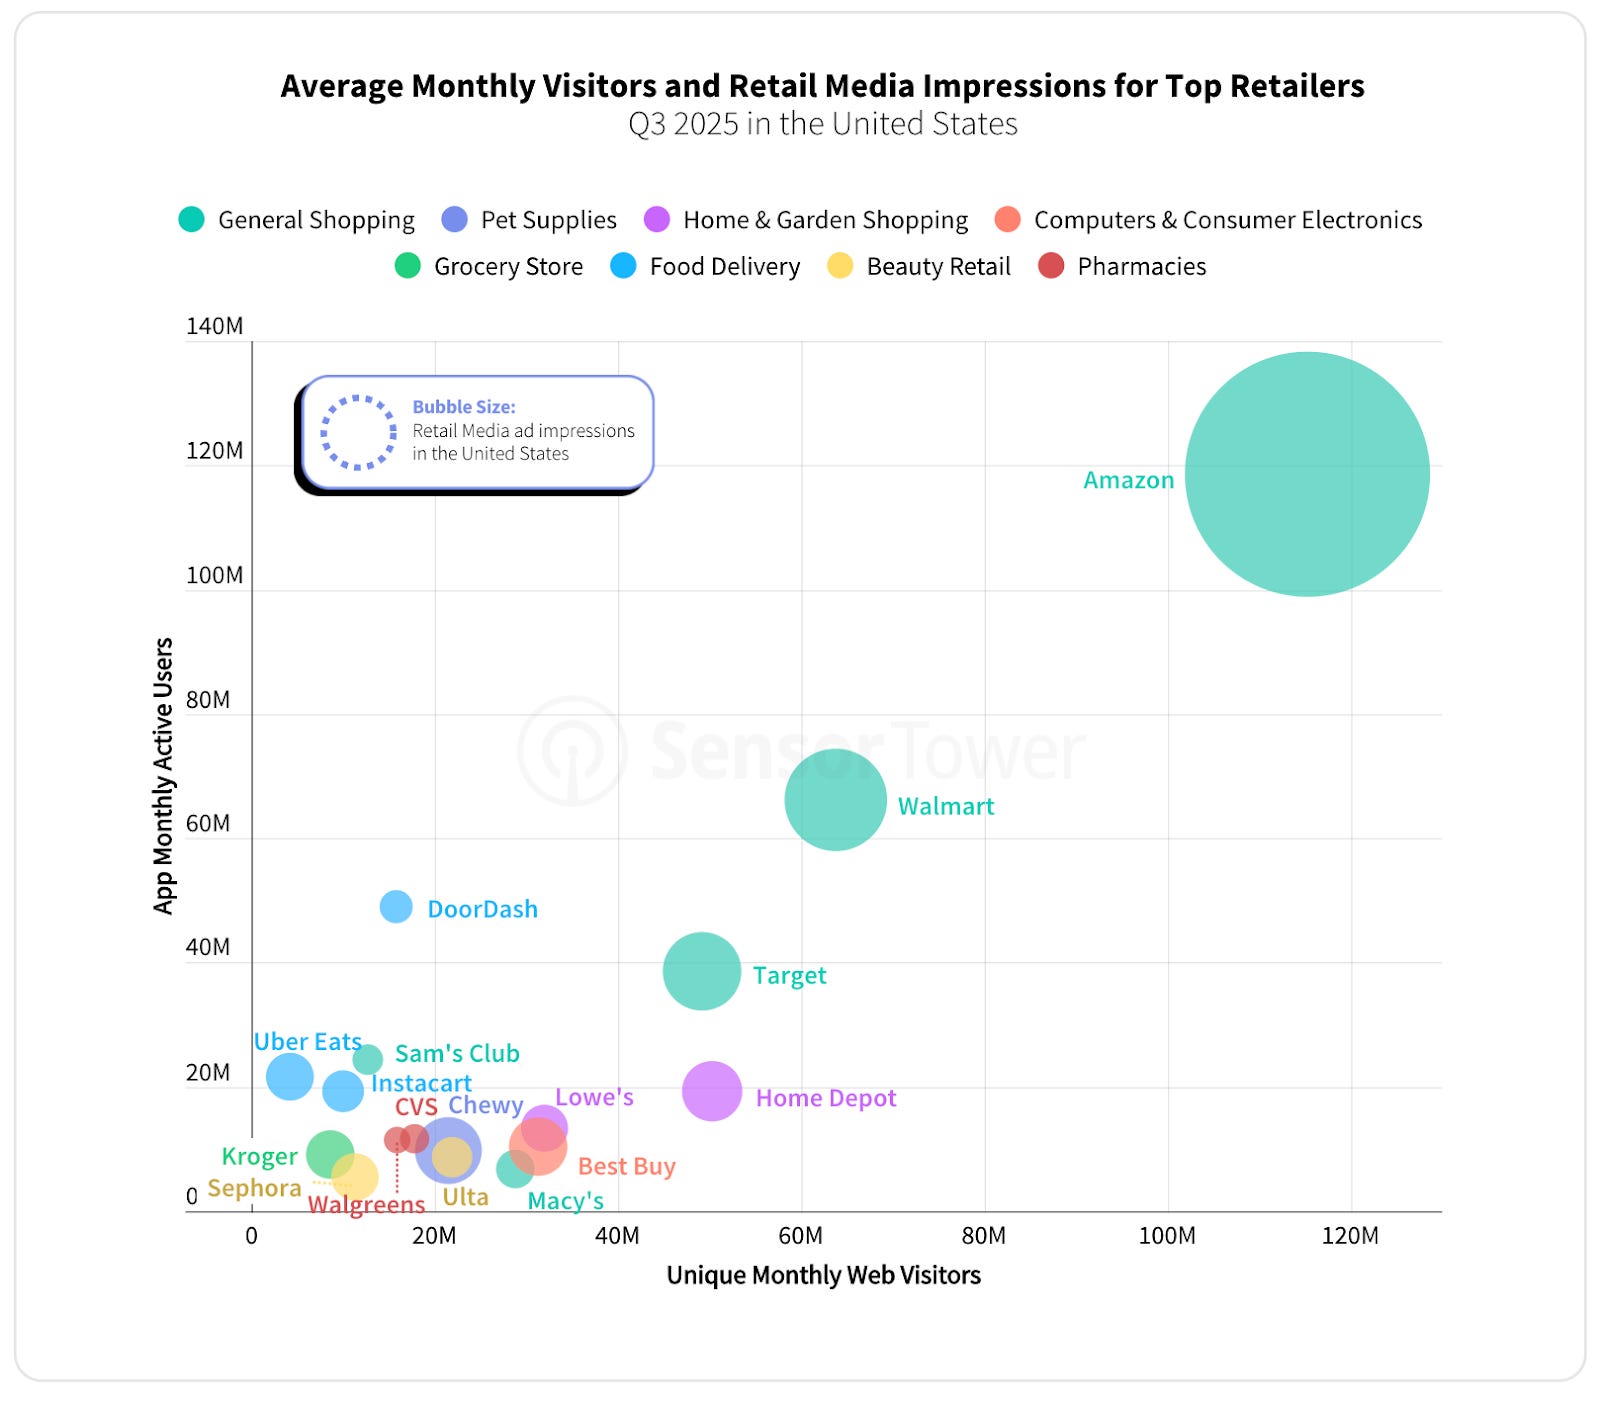
Retail Media Networks (RMN) are the attention economy in action. Retailers have a large audience coming from multiple sources (web + app) made up of high intent shoppers and a captive audience already browsing. They offer an alternative revenue channel for retailers. Capitalizing on this demand, retailers have slots to serve ads based on highly detailed - and personalized - data they have on the user’s shopping habits.
RMN’s convert this attention by showing the user personalized products via ads. The brand - say Amazon or DoorDash - gets a sale from the direct consumer transaction, plus they are monetizing on serving you that ad.
Retail media networks became more valuable in the age of Apple’s App Tracking Transparency (ATT) framework which cut back on IDFA (identifiers for advertisers). In its simplest form, advertisers lost data on user habits - the key to successful mobile advertising tracking. This made first-party data (direct data on consumer habits) which many retailers already had, more valuable. Where advertisers lost visibility, Retail Media Networks gave them a window.
What these trends mean for companies:
Price is still king: consumers are motivated by price and will use all tools to access it, including GenAI.
Mobile is more important than ever in the attention economy. More commerce is coming from mobile than ever. It’s the form-factor we always have on us - a bridge for offline and online. But audiences require more than a channel to capture attention. Attention is not linear - brand presence and values matter. GenAI may direct traffic, but influencers, sponsorships and gamification help to capture and hold attention.
Engagement - offline and online are critical to today’s deal hunters. 73% of Gen Z still prefer to purchase in-store over social commerce (27%). SHEIN shows that social-first features help to mimic community and solidarity.
3. Mobile gaming: a case study in attention. For longtime fan favorites and new titles alike, it’s about maximizing lifetime value
Industry maturation but still a huge opportunity.
For franchises on multiple gaming platforms (mobile game, PC or console) - such as EA Sports FC, Grand Theft Auto, Call of Duty - mobile represents the largest share of downloads due to mobile ubiquity and the low barrier of entry with no additional (and often expensive) hardware needed. Downloads, however, can be particularly expensive with rising user acquisition costs.
Mobile games make revenue from direct consumer purchases (often In-App Purchases (IAP) that go directly through iOS or Google Play stores) or from advertising.
However, In-App Purchases are only part of the revenue story, Direct-to-Consumer (DTC) web stores powered by companies like Xsolla, Appcharge, Stash and Coda are gaining traction. They allow for consumers to transact directly with the gaming company and bypass the app stores. Why do this? Because Apple and Google take a 30% cut of any purchases.
These platforms introduce more complexity but allow gaming publishers to retain higher margins. This is important because they are representing a larger share of the gaming market - meaning publisher revenue is higher than the $82 billion that has gone directly through the app stores. Appcharge reports $700 million in annual transaction volume in 2025 and DTC revenue estimates range from 10% to 25% and higher on a publisher basis. While the aggregate market size of mobile gaming spend is underestimated, the growth rate may still hold at 1% if the DTC purchases follow the same trends as IAP.
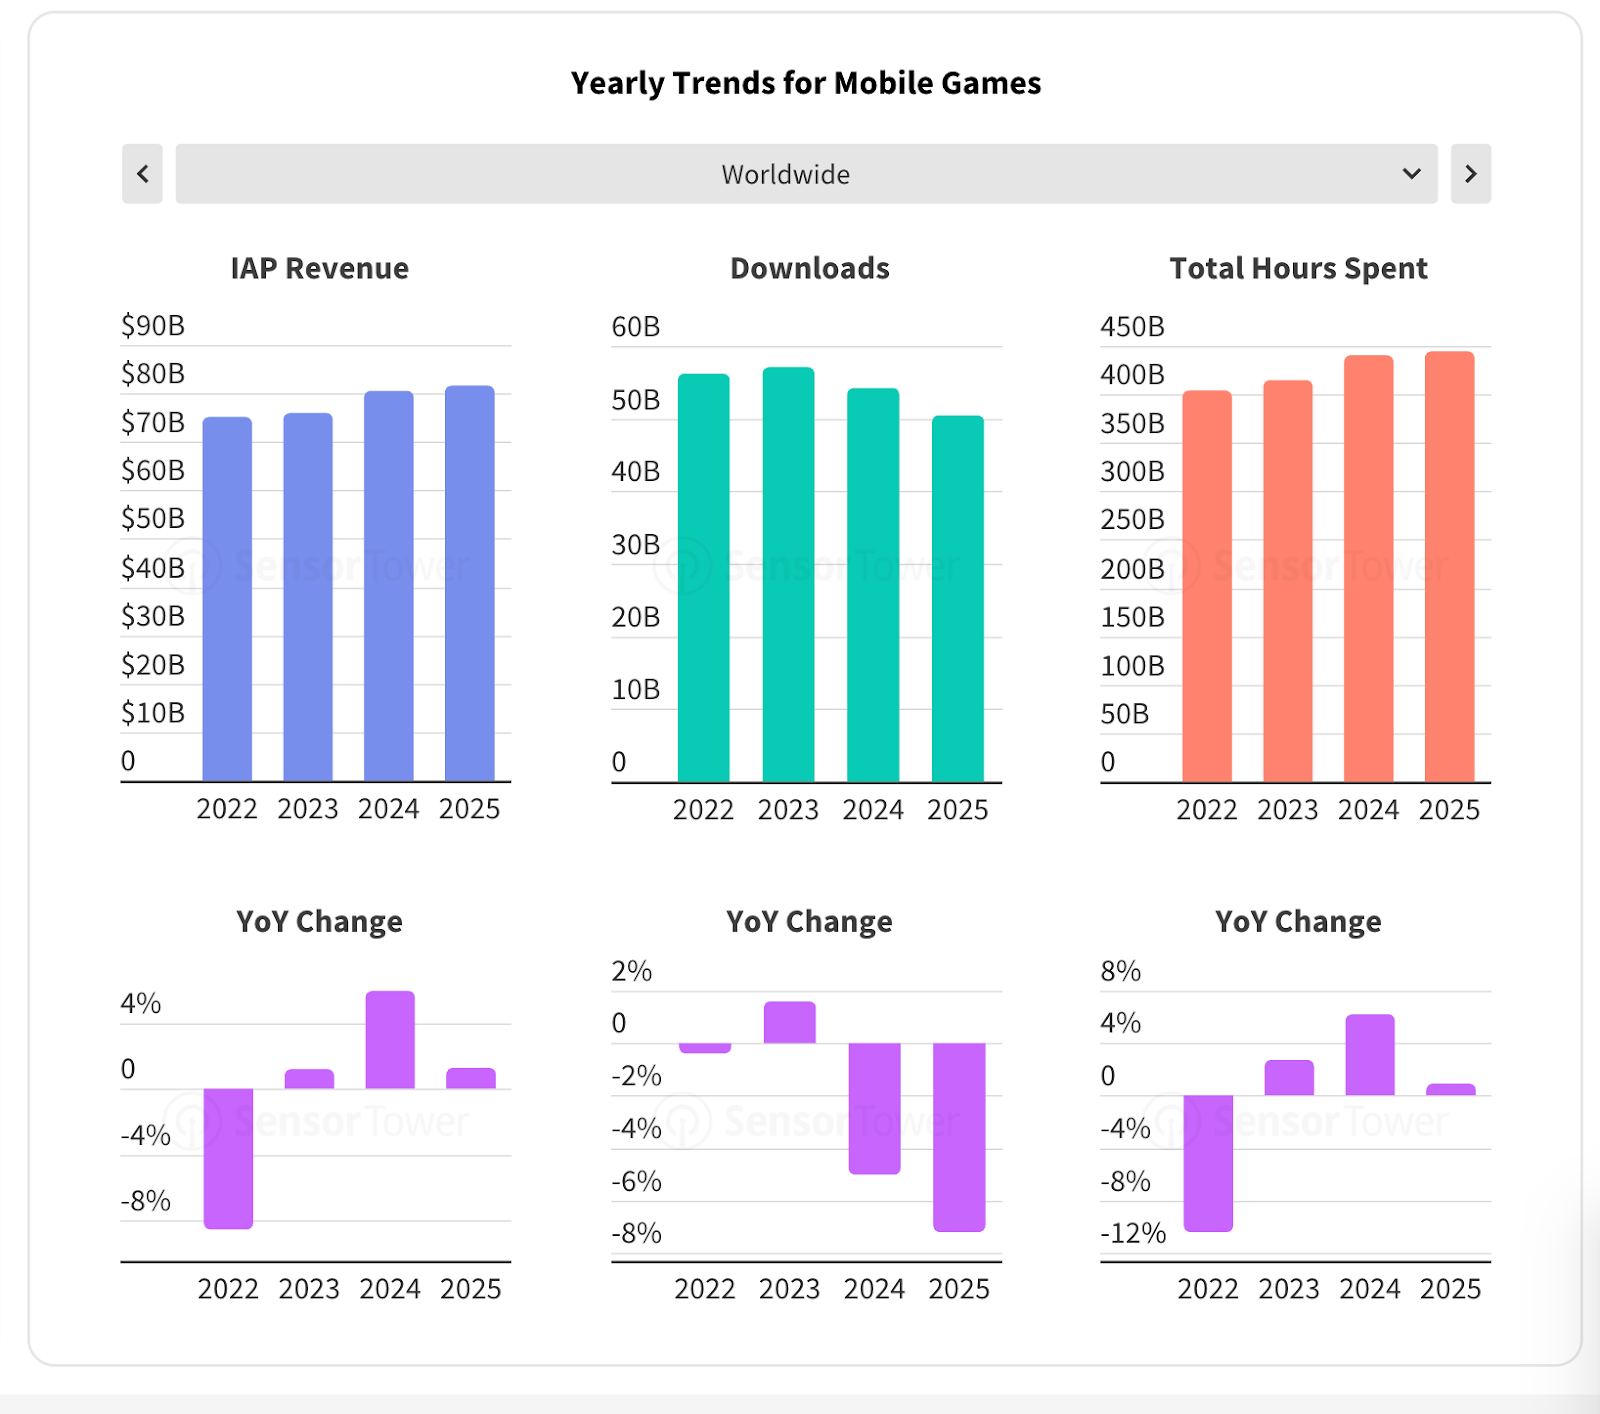
Deeper to the headline growth stats, there are pockets of growth dependent on region and category.


Strategy and puzzle games had strong years for monetization across the board in all regions. Asia, North America and Europe were the largest drivers of IAP spending. For downloads, the Middle East and Africa represented the strongest opportunity for growth. Strategy bucked the trend again - showing that mobile isn’t just about casual or simple games. Core games with more complex mechanics are in high demand - and in competition for time and attention of the masses.
Capturing - and holding - attention in a competitive market
Gaming is more than a strong IP and a catchy game loop. Casual games tend to capture wide audiences, have a simple gameplay and are good candidates for ads. For games monetizing from direct consumer spend, attention and retention are incredibly valuable.
To keep players invested, a rigorous schedule of Live Ops events and mechanics are used. In 2025, there were some shifts in tactics, with a greater emphasis on game progression and social competition features.


This mirrors what we see in the macro gaming trends - moving towards events and mechanics that drive retention, lengthen monetization potential and deepen that social glue.


What does this mean for companies?
Yes, attention is fragmented. Video and mobile games literally wrote the playbook on gamifying attention. However, time is finite and we are seeing maturation in total time spent on mobile, and in games. Games offer sophisticated learnings in creating thrill, delight, anticipation and interaction: recipes for capturing and sustaining attention all the way from ad creatives to milestones, tasks, album collection and tournaments.
Games are not just competing against other games. Short dramas, video streaming, live streaming, even dating and stock trading all have gamified entertainment experiences that compete for attention. Short dramas had a breakout year - quadrupling from <3% of all time in video streaming apps to nearly 11% in Q4 2025 YoY. Video is everywhere, second screening is rampant, and content is evolving - with speculation that companies are simplifying scripts to cater to half-attentive viewers. It’s important to monitor trends at large to spot shifts in how users consume across all sectors of mobile: be it short bursts, multitasking or rewarded daily check-ins.
Games still have audiences of highly engaged players with an appetite for digital consumption. Even with more competition for mindshare, they offer audiences for collaborations, sponsorships or live ops events that tie back to real-world tentpole events like the Olympics, Premiers League Championship or movie premieres.
So what truly is the state of play for mobile in 2026?
Mobile has a firm grip on our attention. It has become a mainstay in our daily habits by giving us access to the internet at any moment. We’ve all felt the rush of panic when we’ve left our phone behind.
Whether we are crushing candy while watching Stranger Things, checking email in line at the post office, or binging TikTok explainers, mobile is our access point to knowledge, purchases and entertainment.
To win on mobile is to win with consumers. But in a maturing industry it can be harder to earn space on someone’s phone and even harder to stay top of mind.
Knowing what platforms to prioritize and the techniques to incorporate on mobile is table stakes in our mobile-native attention economy.
We can help you get there. To start, the State of Mobile 2026 report is free to download.
And we’ll be publishing more data-driven takes on what’s really capturing attention. We will be dissecting how mobile, gaming, news, social media and advertising intersect in the attention economy to influence what we think, what we buy and how we live.