


The Underline:
In Short: Bending Spoons went public on July 1st at an $18.4 billion valuation and closed the week near $23 billion. We breakdown why their app empire has staying power.
So What: Their business model places value in the hardest-won currency of our time: attentive audiences, but carries inherent risks of alienating these very users.
Bending Spoons’ Nasdaq IPO Generated $1.68 Billion in Proceeds
On July 1, 2026, Bending Spoons, the Italian company that owns AOL, Evernote and Eventbrite, listed on Nasdaq at a $18.4 billion (USD) valuation.
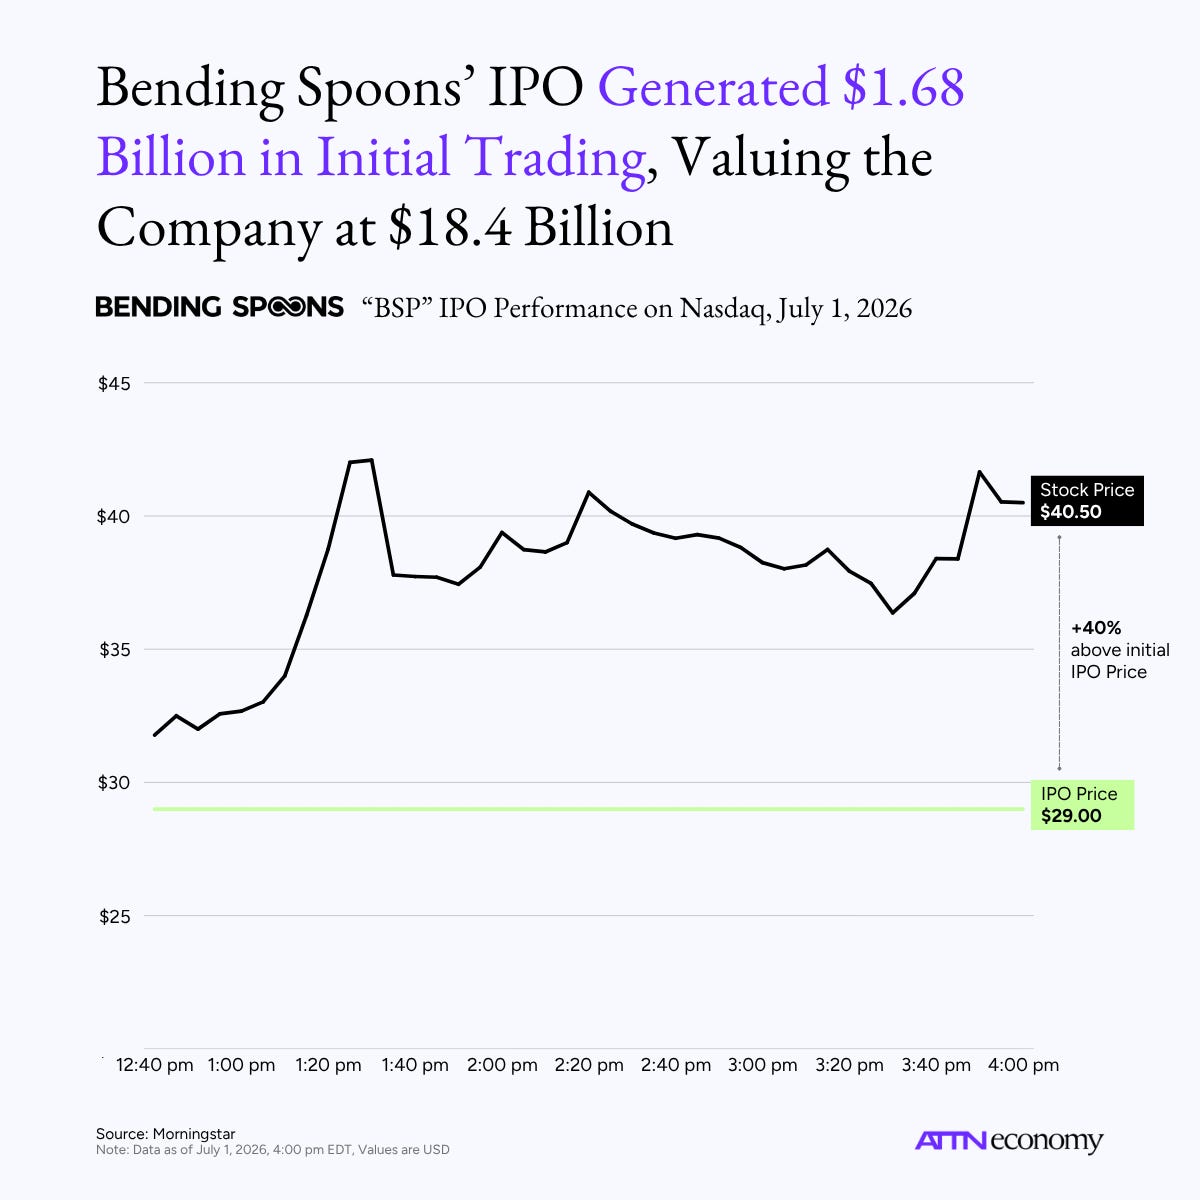
Just two days later, they closed out the week trading 24% above the IPO price approaching a $23 billion valuation.
The company self-describes as “private equity had a baby with Google.” Meanwhile, most describe them as a company that buys “bygone software”, “struggling brands” and “internet has-beens” with the aim of long-term growth.
But this is not the most interesting read on their business model.
What is the Bending Spoons Business Model?
Contrary to the headlines, they’re not in the business of buying languished brands and tech flops.
They are in the business of buying audiences.
We spoke with BBC News Business Today (Aired July 2, 2026) on why this business model works:
Bending Spoons bought existing engaged audience bases.
Then, they optimize those existing bases with their people and their tech to create better user experiences and monetize users, largely through in-app subscriptions.
In an attention economy, audiences are the most hard to acquire assets.
Building these audiences is even harder now that the barrier to create an app is nearly gone with the rise of vibe coding and agentic coding. It’s difficult, and expensive, to get people to know the app exists, convince them to download it and then to not only stick around but keep coming back.
Bending Spoons’ model skips this part, and instead tweaks and improves from existing brand equity accrued from an existing base.
Does the Bending Spoons Playbook Work?
Over the last 10 years, they’ve acquired largely mobile-first businesses with over 50 in their portfolio, many of which are known but not category leaders.
Most importantly, they seek product-market fit. This is shown by active users (across both apps and websites) and revenue coming in from users.
Unlike most private equity companies, they buy them with a long-term view of holding these assets “forever”, not turning them around quickly.
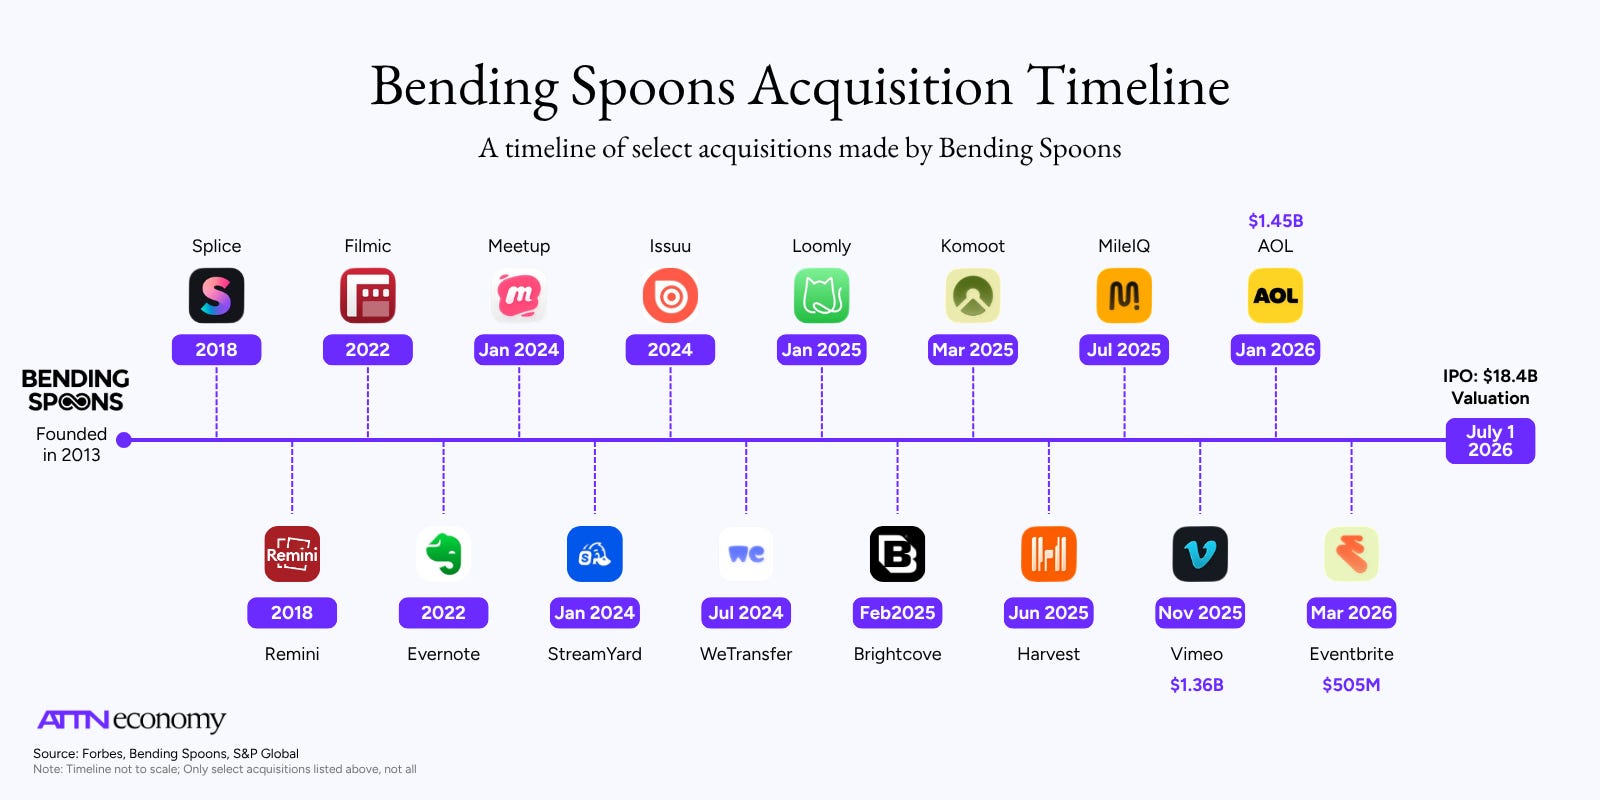
From there, they optimize performance of the app, largely through AI and data-fueled proprietary technology, coupled with their industry expertise from their team who have honed skills and playbooks in user experience, monetization and feature testing.
They basically create a portfolio of apps that benefit from synergies across these two areas:
Their Technology: They use their technology - built on a blend of big data and powered by AI - to test, iterate and relaunch apps quickly with the aim of monetizing them through in-app subscriptions. This could include using “Pico” to A/B test app features, “Minerva” to predict lifetime value, “Xina” to attribute marketing campaigns and “Matrix” swiftly validate UX patterns. They could, for example, quickly test the willingness of a user to pay, and then maximize the price offered as well as the bundle of features and the billing frequency (weekly, monthly, annually). All to achieve optimal, unrealized revenue.
Their People: After acquisition it’s widely reported that there are often rounds of layoffs at the acquired company. In the case of Vimeo, this was a large portion of the company. Bending Spoons then leverage the industry subject-matter expertise from their internal team, relying on their know-how across app store optimization, user acquisition, subscription monetization, mobile-first UI/UX and AI features. Ultimately they have gotten very good at optimizing digital experiences to monetize existing audiences.
Is an AI-First Approach Making Their Portfolio Companies More Efficient and Agile?
It is efficient by not having say one UX team for AOL and one for Evernote.
They are able to instead apply their UX team and tools (e.g. Matrix) for making this process faster and more robust across all of their portfolio of apps. Under the hood, the apps work similarly and they can repeat these playbooks across industries.
Case Study: Evernote
Evernote was one of their first high-profile acquisitions in January 2023.
Evernote by numbers:
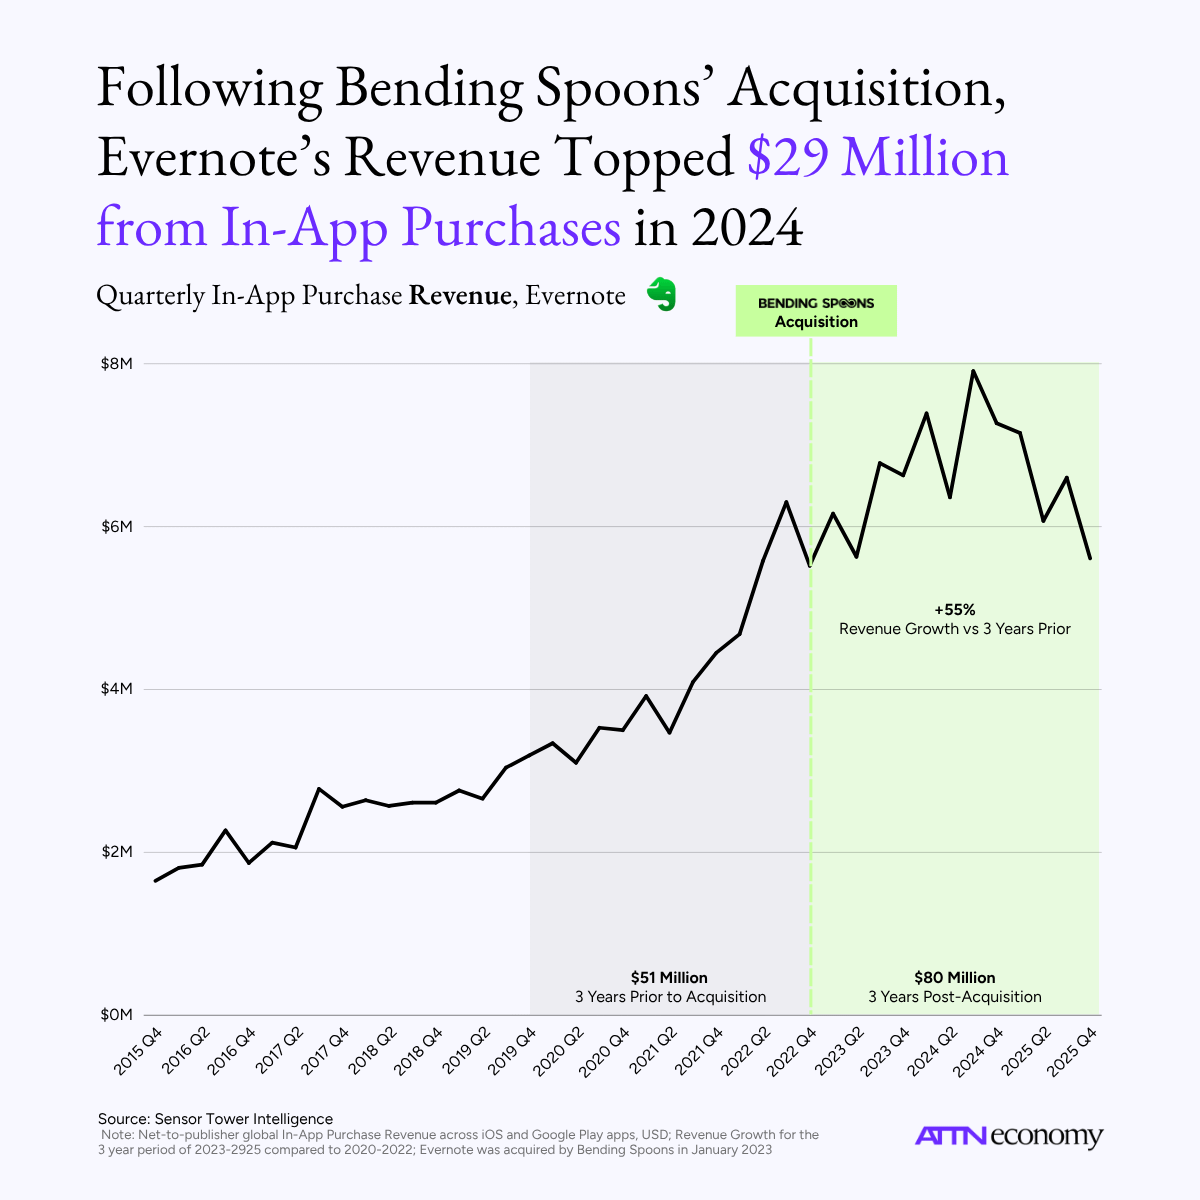
In the year prior to Bending Spoons acquisition (2022), Evernote had made $22 Million through in-app purchase revenue of monthly and yearly subscriptions, totalling $51 Million for the three-year period of 2020 to 2022.
Post-acquisition, Bending Spoons increased this revenue by 55% to nearly $80 million over the course of the three years. Annually, revenue peaked at $29 million in 2024.
They did this by:
Repackaging the subscription features
Changing payment periods from monthly and yearly to weekly and yearly
Repositioning the paywall in the user onboarding journey
Increasing subscription prices from 50% to nearly 300% (an annual membership of $63.99 increased to $249.99 USD)
However, while revenue grew, the user base shrank.
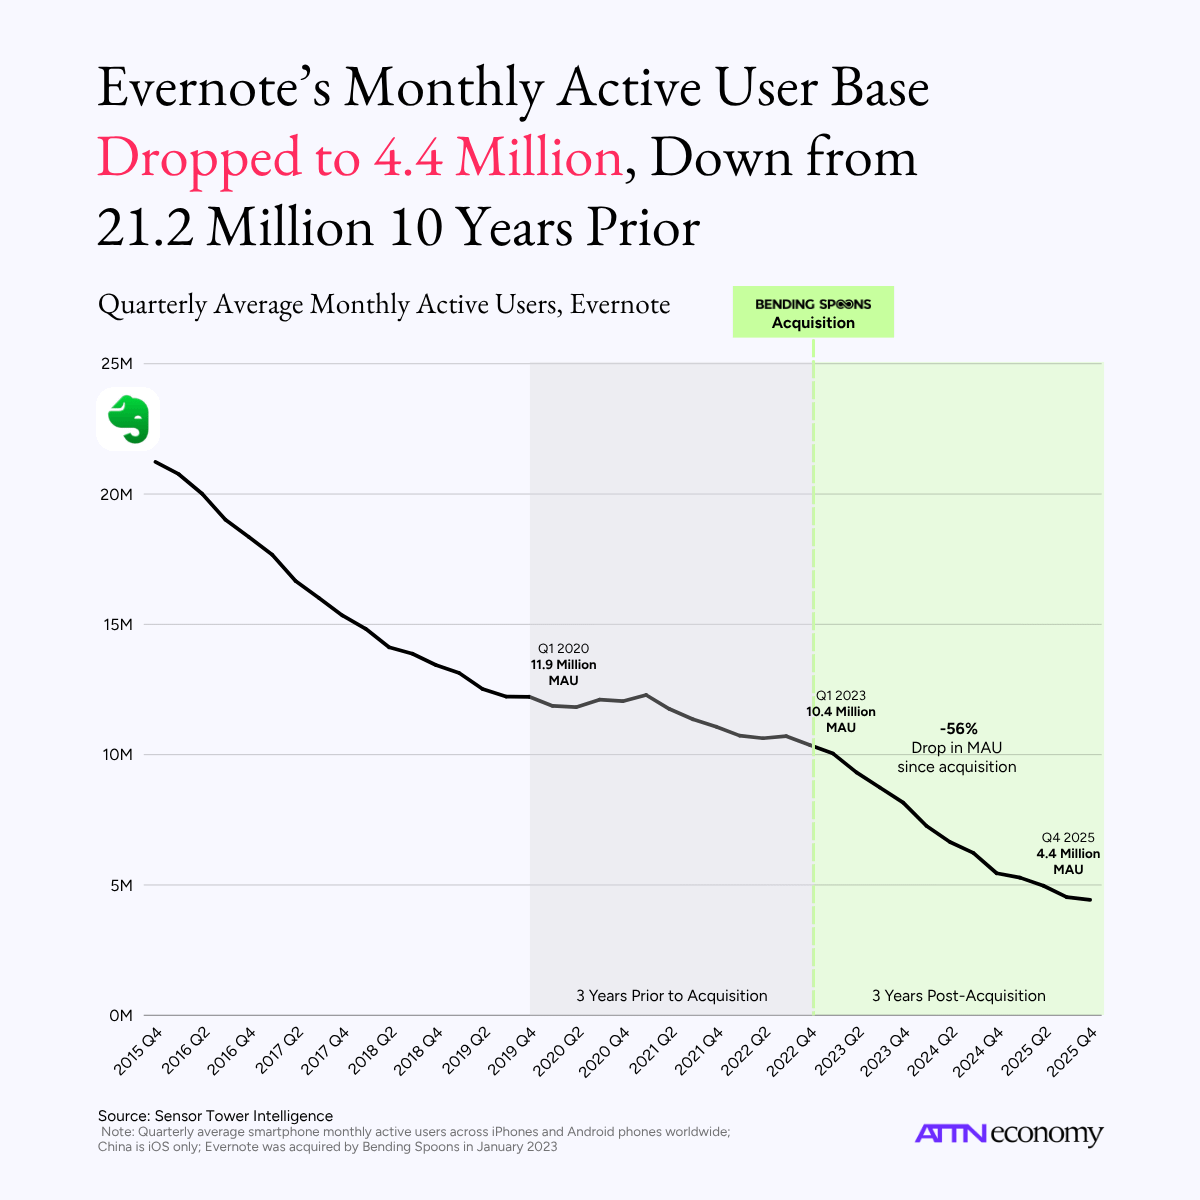
Monthly active users (MAU) of Evernote’s app dropped 55% post-acquisition, an acceleration on the 15% drop it had seen over the course of the three years prior.
And notably, sentiment dropped:
Prior to acquisition: (July 2008 - Dec 2022): 4.2 / 5 stars with only 12% 1-star reviews
After acquisition (Jan 2023 - June 2026): 2.4 / 5 stars with 54% 1-star reviews
According to mobile app data from Sensor Tower.
There is an inherent risk in this business model of alienating the very audience they paid to acquire.
To summarize the data, post-acquisition Evernote’s app saw:
Price hikes in subscriptions from 50% to 300%
In-App Purchase Revenue grew +55%
App MAU dropped -55%
Sentiment plummeted: 1-star reviews went from 12% to 54% of total app ratings
Despite higher revenue futures, this means you have a smaller pool of users to convert to paid subscribers, and a worrisome trajectory for future revenue growth.
Where the Bending Spoons Model Works
Mobile-First Focus: Bending Spoons have honed both skills and proprietary technology in driving mobile app revenue and subscription-based businesses. Mobile is the most popular device in the world and apps are the portals to living, working and engaging in today’s mobile-first society. A narrow aperture here in a large market offers a strong advantage to scale across a portfolio of app-based businesses across a variety of sectors - from video to weather to ticketing to news and email.
Industry Tail Winds: Consumer spending in In-App Purchases in mobile apps has hit a new high at $85 Billion in 2025 alone, up 20% year on year, following on a strong trend: a 5-Year CAGR of 23%. People aren’t just spending time in these apps. They’re spending money because these apps have become load-bearing walls in how they work, create, communicate and make decisions. Mobile’s share of wallet is set to increase into 2027.
Cross-Promotion Across Portfolio: Many of the apps they acquired are in distinct categories and serve different needs. Bending Spoons can fuel growth in audiences and expand into new markets by tapping into this broad global base of users across products. It’s the same reason why Threads had such a successful app launch in 2023 - Meta was able to springboard off of Instagram’s existing 2.1 Billion user base.
Shared Infrastructure: Best practices in UX, monetization bundles, paywall placement and notification cadence can be applied across the entire portfolio since the apps run on similar technology underneath. When Bending Spoons acquires a company with novel tech or proprietary data, that gets folded into the shared stack too, so every acquisition makes the next one faster to optimize rather than starting from scratch.
Where the Model Breaks
Alienating the User Base: the challenge is that if you have a dissatisfied audience and a shrinking audience, then your pool of free users to convert to paid shrinks. Instead, you have to get more from the existing paying users through things like further price hikes or rebundling of features. It’s harder to see long-term revenue growth.
Growing Audiences: This means you are back in the hard area of user acquisition to rebuild that base - which is expensive, competitive and time intensive. We wrote more on that here.
Over-rotating on Monetization versus Engagement: In the case of Bending Spoons, they are very good at monetizing existing app bases through in-app subscriptions. However, too much emphasis here can leave them exposed. Focusing on engaging users and delivering value will help foster a greater long-term play for retention, lifetime value and minimizing lapsed users - to avoid the trap of having to regrow the very bases they acquired.
Reputational Risk: While they aren’t necessarily replacing teams with genAI tools and agents after acquiring a company, layoffs following a deal are common and well documented. The company is operating in a moment when AI is already a flashpoint for public trust, there is a risk they get caught in this narrative - one that is contributing to widespread anti-AI sentiment.
Potential Regulatory Exposure: Bending Spoons has acquired 50+ platforms with many major consumer brands. Now that they are a public company, they may draw more scrutiny on market concentration or data practices across their portfolio, especially given their EU roots.
What This Means for the Future
Bending Spoons focus on execution of revenue generation to an existing audience base is a compelling strategy in an attention economy. They can hone in, focus on this piece of the puzzle and demonstrate expertise and precision learning - then rinse and repeat.
However, taking on legacy brands and non-market leaders can mean you inherit a leaky bucket of users, and while monetizing them more efficiently is good for the short-term, it leaves them exposed to alienating this base through price hikes.
Retention needs to be baked into the equation in order to preserve the ability to move free users to paid. Otherwise they are back in the aggressive, competitive and expensive user acquisition game. The big concern here is trust, especially for long time users of the brand.
On a positive note, Bending Spoons has recently acquired digital properties with strong mobile bases (true to its thesis) but also with substantial web presence and strong brand recall and brand equity.
AOL is the 4th largest news app in the US by daily active users. Globally, 18.3 Million unique visitors go to AOL.com across web (desktop or mobile) and app - 79% of those only use the website, according to Sensor Towers’ Web Insights.
This shows they are expanding beyond purely mobile bases, but to properties with strong app user bases and a healthy web presence.
There is ample opportunity to then convert these web users to app users through a more personalized, easier to use app experience.
It’s a built in funnel for expansion to do what they do well: monetize an app base.
Disclaimer: This piece is provided for informational purposes only, and should not be relied upon as legal, business, or investment advice. Feature Image: Michael Nagle/Bloomberg via Getty Images / Getty Image
For more on the mobile economy:


Very interesting and seemingly very smart play by Bending Spoons to invest in engaged audiences. Also great insight and breakdown of their playbook!
The Evernote numbers say it all: revenue up 55 percent, but MAU down 55 percent and 1 star reviews up from 12 to 54 percent. That is not a coincidence, it is the bill coming due for treating an acquired audience as a monetization target instead of a product worth improving.
I review subscription apps at App Audit Weekly and this is basically the failure mode I flag most often: price goes up, perceived value does not.